Rent in Florida can already take a considerable bite out of your paycheck. The average rent in the state is about $1,955 a month, around $220 more than the national average. A surprise bill for a ruined couch, TV, or a closet full of clothes is the last thing you'd want in your budget.
Your landlord's insurance covers the building. Your belongings are on you. If a kitchen fire, a burst pipe, or a break-in hits your unit, the replacement bill lands on you.
That gap is especially important to consider in Florida. The state ranks third highest in the country for natural disaster risk, and hurricane season returns every year. Despite this, only about 40% of Florida renters have a policy. The fix is simple and affordable: getting your own renters insurance policy.

This guide covers what renters insurance costs in Florida, what it covers, what it leaves out, and how to choose a plan without overpaying.
Florida's renter landscape
Renters vs. homeowners: Florida vs. United States
- Florida: About 32% (roughly 2.9 million) of households rent.
- United States: About 35% (roughly 45 million) of households rent.
Florida's share is a little lower than the national share. Still, millions of households face the same question: how do they protect their belongings?
Share of renters and owners
Share of occupied housing units, 2024
Share of renters with active policies: Florida vs. United States
- Florida: About 40% of renter households have a policy.
- United States: About 48% of renter households have a policy.
Florida ranks 42nd out of the 50 states and Washington, D.C. on this measure. Put simply, about six in ten Florida renters don't have a policy, even in a state that ranks third in the country for natural disaster risk.
Share of renters with an active renters insurance policy
Estimated share of renter-occupied households with an HO-4 policy, 2022
What does renters insurance cost in Florida?
Average renters insurance cost: Florida vs. United States
On average, Florida renters pay a little more than renters nationally. Yet the monthly cost is still small compared to almost any other bill in your budget.
- Florida average: $27 per month ($324 per year)
- National average: $23 per month ($276 per year)
That's less than $1 a day, or about the price of two coffees a week, to protect what you own.
2026 average renters insurance cost
Florida vs. National
| Monthly cost | Annual cost | Difference vs. national | |
|---|---|---|---|
| Florida average | $27 | $324 | +17% |
| National average | $23 | $276 | – |
A few things can move your price up or down:
- Location: Your ZIP code, distance from the coast, and local storm risk all play a role.
- Building: Age, construction, and safety features can change your rate.
- Coverage amount: Higher limits usually cost more.
- Deductible: A higher deductible usually lowers your premium. Some Florida policies also carry a separate hurricane deductible.
- The insurance company: Companies price risk differently, so compare quotes.
Comparing insurance costs to rent: Florida vs. United States
Insurance coverage is a small line in the housing budget, even in a state where rent runs above the national average. Setting the average rent next to the average premium shows how little protection costs by comparison.
Florida:
- Average monthly rent: ~$1,955
- Average monthly renters insurance cost: ~$27
- Insurance cost as percentage of rent: about 1.4%
United States:
- Average monthly rent: ~$1,733
- Average monthly renters insurance cost: ~$23
- Insurance cost as percentage of rent: about 1.3%
Florida renters pay about $4 more per month than renters at the national level do, but because rent here is higher too, coverage takes nearly the same slice of the budget.
Rent vs. insurance cost
Florida vs. National
| Avg. monthly rent | Avg. monthly insurance | Insurance as % of rent | |
|---|---|---|---|
| Florida | $1,955 | $27 | 1.4% |
| National | $1,733 | $23 | 1.3% |
How much coverage do renters choose?
Across the United States, the most popular personal property coverage level falls in the $20,000 to $24,999 range. Florida renters tend to start with a lower coverage level, $10,000 to $14,999.
The top five personal property coverage ranges in Florida are:
- $10,000 to $14,999
- $15,000 to $19,999
- $20,000 to $24,999
- $30,000 to $34,999
- $25,000 to $29,999
Together, the top three ranges account for about two-thirds (66%) of Florida renters insurance policies.
Try a quick home inventory. Walk room to room with your phone and record a video of everything you would need to replace. Then total the replacement costs. That number is your starting point.
Renters insurance coverage amounts preferred by renters in Florida
Share of HO-4 policies by personal property coverage range, top five ranges
- $10,000 to $14,99927.0%
- $15,000 to $19,99920.7%
- $20,000 to $24,99918.6%
- $9,999 and under8.4%
- $30,000 to $34,9998.2%
- All other ranges17.0%
Is renters insurance required in Florida?
No federal or Florida state law requires renters to carry it. Many landlords, however, make it a lease rule. If your lease requires coverage and you skip it, you could be in violation of your rental agreement.
Even when nobody requires it, going without puts you at risk in three ways:
- Your landlord's policy does not cover your belongings.
- You could be personally responsible if someone gets hurt in your unit.
- You would pay for temporary housing yourself if a covered loss forced you out.
What does renters insurance cover in Florida?
A standard renters policy, known as an HO-4, has three main parts.
1. Personal property coverage
Personal property coverage, also known as contents coverage, pays to replace your belongings when a covered event damages them, such as:
- Fire, smoke, or lightning
- Theft or vandalism
- Windstorm or hail
- Sudden water damage, like a burst pipe
Covered items typically include furniture, electronics, clothing, and kitchen appliances.
2. Liability coverage
Say a guest slips on your wet floor or your dog bites a neighbor. Liability coverage helps pay their medical bills, legal fees, and any settlement. It protects your savings, not just the injured person.
3. Loss of use
If a covered event makes your unit unlivable, the loss-of-use coverage, also known as Additional Living Expenses, helps pay for a hotel or temporary rental, meals, and other extra costs while your place is repaired.
What are the biggest risks in Florida?
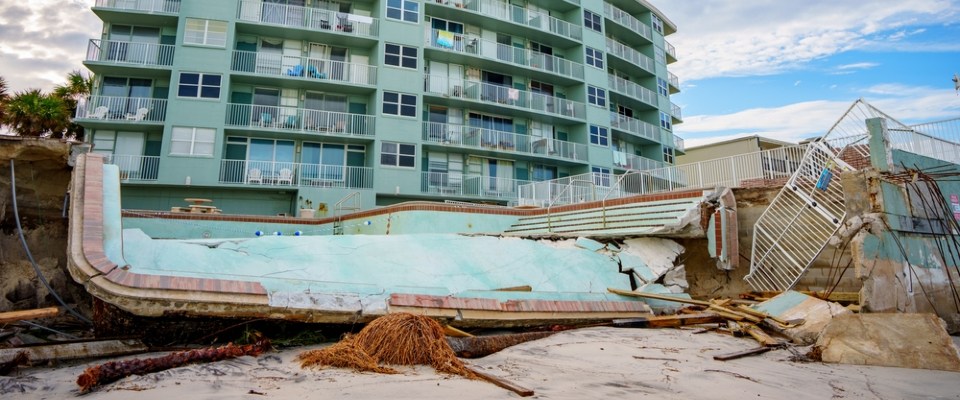
Florida ranks third highest out of 56 states and territories on FEMA's National Risk Index, with a composite score of 96.4 out of 100. FEMA scores each hazard from 0 to 100 based on expected annual losses. Florida's top scores are:
- Hurricane: 100
- Coastal flooding: 100
- Lightning: 100
- Tornado: 96
- Strong wind: 94
Inland flooding also scores high, at 93.
Renters insurance coverage amounts preferred by renters in Florida
Share of HO-4 policies by personal property coverage range, top five ranges
- $10,000 to $14,99927.0%
- $15,000 to $19,99920.7%
- $20,000 to $24,99918.6%
- $9,999 and under8.4%
- $30,000 to $34,9998.2%
- All other ranges17.0%
What a standard policy covers, and what it doesn't
Wind damage from hurricanes, tornadoes, and strong storms is generally covered under the windstorm part of your policy. Lightning is covered too. Some Florida policies carry a separate hurricane deductible, and Florida law requires the dollar amount to appear on the declarations page of policies that have one.
Flooding is the big exception. Standard renters insurance does not cover flood damage from coastal flooding, heavy rain, or storm surge.
Choosing the right renters insurance
Here are the main factors you should consider to help you find the right renters insurance:
- Start with convenience. You should be able to sign up online and get proof of insurance right away, so you can send it to your landlord the same day. Look for plans created for renters, not homeowner policies with a renter label.
- Easy management matters, too. Updating coverage, filing a claim, or canceling should work through an app or website, not an 800 number that stops answering at 5 p.m. Ask your property manager whether they require a specific provider.
Because this is Florida, ask two more questions:
- Is there a separate hurricane deductible?
- How can I add flood coverage?
Before you sign, read the declarations page. It’s the one-page summary of what you have and what you don't.
Key takeaways:
- About 40% of Florida renters have a policy, compared with 48% of renters nationally, even though Florida ranks third highest for natural disaster risk.
- The average policy costs about $27 a month, roughly 1.4% of the average rent.
- Most Florida renters choose between $10,000 and $24,999 in personal property coverage. A home inventory helps you pick your range.
Frequently asked questions
A: Partly. Wind damage to your belongings is generally covered. Flooding and storm surge are not. Ask whether your policy has a separate hurricane deductible, and check the dollar amount on your declarations page.
A: No. You need a separate flood policy. Renters can buy contents-only coverage through the NFIP or ask a private insurer. Most NFIP policies have a 30-day waiting period.
A: Usually, yes. A policy also includes liability and loss-of-use coverage, which protect you from costs that have nothing to do with how much stuff you own. The most common Florida policies carry $10,000 to $24,999 in belongings coverage, so even a modest apartment adds up faster than people expect.
A: It depends. Loss-of-use coverage pays when a covered event makes your unit unlivable. Policies differ on whether a mandatory evacuation with no damage qualifies. Ask your insurance company before hurricane season.
Methodology
This article's data was compiled by our analytics team using publicly available housing statistics, insurance industry reporting, aggregated market averages from recent years, and market intelligence provided by our sister company, Yardi Matrix. Cost estimates reflect statewide averages and may vary by city, building type, and coverage limits. All figures are intended for educational purposes and should be used as general guidance when evaluating renters insurance in Florida.
Sources
- The Insurance Information Institute. Average Homeowners Losses, 2019–2023. https://www.iii.org/table-archive/20887, accessed on October 20, 2026.
- National Association of Insurance Commissioners (May 2025). Dwelling Fire, Homeowners Owner-Occupied, and Homeowners Tenant and Condominium/Cooperative Unit Owner’s Insurance Report: Data for 2022. https://content.naic.org/sites/default/files/publication-hmr-zu-homeowners-report.pdf, accessed on October 20, 2026.
- Lindsay Bishop. Average Cost of Renters Insurance (Updated: 2026). https://www.valuepenguin.com/average-cost-renters-insurance, accessed on October 20, 2026.
- US Census Bureau. American Housing Survey (AHS). https://www.census.gov/programs-surveys/ahs/data/interactive/ahstablecreator.html, accessed on October 20, 2026.
- The Federal Emergency Management Agency (FEMA). National Risk Index Data (Dec 2025). https://www.fema.gov/about/openfema/data-sets/national-risk-index-data, accessed on October 20, 2026.